Cost to Open a Company in Italy: Real Breakdown 2026
Planning to open a business in Italy? Start with the public charges you can identify, then obtain quotes for the work your file requires. The illustrative table below adds up to €855.87 to €875.87 for an ordinary SRL, or €609.87 to €629.87 for an SRLS using the standard deed; it is not an all-inclusive first-year price. The company setup-cost planner lets you organise itemised figures from your own quotes by legal form. For the sequence see the step-by-step guide; for liability and tax trade-offs see the SRL versus sole proprietorship comparison.
Fixed public charges for an SRL in 2026
Illustration: cash contributions, capital no higher than €516,456.90, one registered office and the Chamber annual fee shown below. These taxes do not depend on the founders' residence. The subtotal covers only the listed charges, not every first-year expense: separate filings, local measures, company-book stamping, extra copies and activity-specific permits can add costs. Confirm the competent Chamber's current amount and the notary's itemised disbursements. The SRLS exemptions described here concern the standard deed signed in person; obtain a separate quote for videoconference incorporation.
| Item | Ordinary SRL | SRLS, standard deed | Paid to |
|---|
| Registration tax on the deed of incorporation | €200 | €200 | Revenue Agency, through the notary |
| Stamp duty on the deed, including the Business Register application | €156 | exempt | Revenue Agency, through the notary |
| Business Register secretarial fee, electronic filing | €90 | exempt | Chamber of Commerce |
| Chamber of Commerce annual fee, year of registration | €100, or €120 with the 20% increase | €100, or €120 with the 20% increase | Chamber of Commerce |
| Annual tax on company books, capital up to €516,456.90 | €309.87 | €309.87 | Revenue Agency |
| Subtotal of the listed charges | €855.87 to €875.87 | €609.87 to €629.87 | |
The registration tax is the fixed amount under the Registration Tax Code (Tariff, Part I, art. 4). The €156 stamp duty is the flat amount for company deeds registered electronically under the Stamp Duty Tariff (art. 1, para. 1-bis.1). The annual fee for companies registered during 2026 is €100, raised to €120 by the Chambers authorised to apply the 20% increase for 2026 to 2028, as published by the Chamber of Commerce of Bergamo. The tax on company books is the flat government concession tax under the Tariff annexed to D.P.R. 641/1972 (art. 23); it rises to €516.46 when share capital exceeds €516,456.90.
Share capital is not in the table because it is not a cost: it is paid into the company. The notary's fee is not in the table either, because for an ordinary SRL there is no public tariff and each notary quotes the deed; for an SRLS with the standard deed no notarial fee is due.
Build an itemised budget by structure
There is no single mandatory formation price for a foreign founder. Separate public charges (specific to the filing and competent Chamber), professional fees (quoted for a defined scope), operating costs (which depend on your activity) and share capital (paid into the company, not a fee). Do not add every possible line below to every case.
| Structure | One-off items to request in a quote | Recurring items to plan | Not part of an incorporation-fee total |
|---|
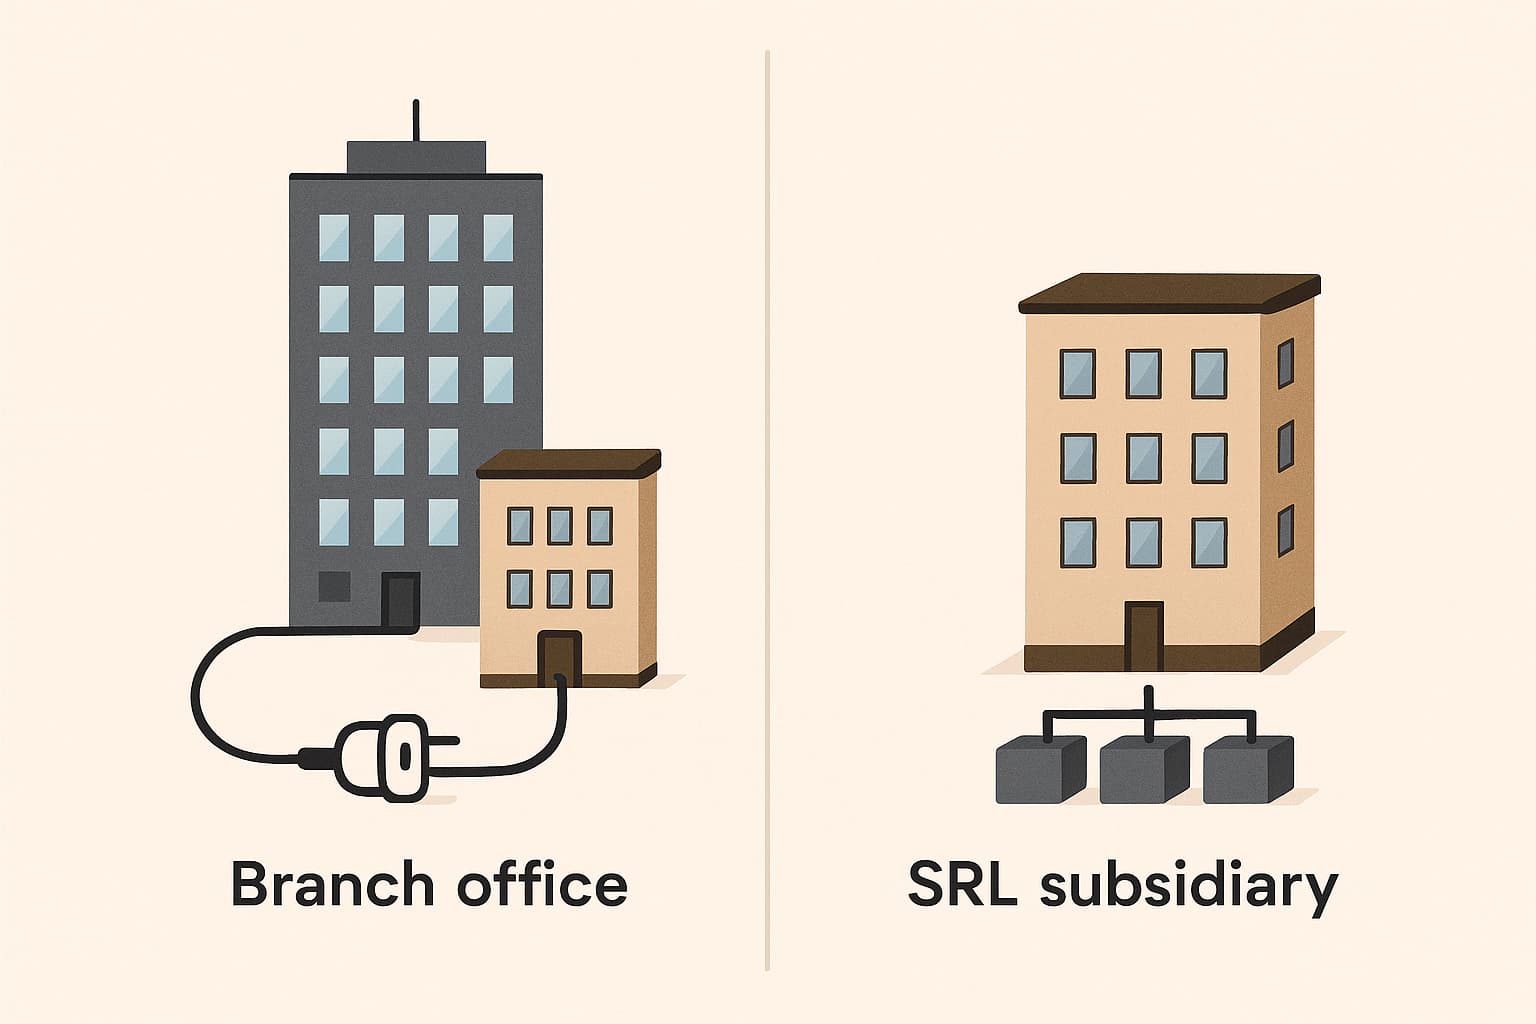
| Sole proprietorship | Applicable Business Register filing, sector authorisations, optional setup assistance | Applicable Chamber annual duty, PEC/digital services, accounting and INPS by activity | Personal income tax, VAT where due, permit costs and working capital |
| SRLS | Standard notarial public deed; any charges not covered by the statutory exemption; optional assistance | Chamber annual duty, accounts, digital services and any role-dependent social contributions | Capital paid in (€1–€9,999.99), payroll, guarantees and immigration costs |
| SRL | Notarial deed and its itemised taxes/outlays, Business Register filing, optional setup assistance | Chamber annual duty, accounting, filing of accounts, digital services and any role-dependent social contributions | Capital paid in (from €1), tax on profits, payroll and immigration costs |
Sole proprietorship
There is no required share capital, but personal liability extends to business debts. VAT-position opening and Business Register enrollment are different steps: whether you need the latter and which public charges apply depends on the activity. The Partita IVA guide covers registration and tax-regime eligibility. Do not treat a fee quoted for an accountant's setup as a government fee.
An SRLS still requires a notarial public deed under art. 2463-bis of the Civil Code. The standard ministerial deed has the exemptions from stamp duty, registry secretarial charges and notarial honoraria under art. 3(3), D.L. 1/2012. Ask which other taxes, disbursements and optional professional services remain. The shareholders must be individuals; the cash capital is from €1 to less than €10,000, paid in full at incorporation. Standard clauses cannot be customised.
SRL: request the same scope from each notary
An ordinary SRL's notarial fee varies by deed, governance, parties and special provisions; a statutory capital of €10,000 is not a mandatory cash expense. Under arts. 2463 and 2464 of the Civil Code, an SRL can start with €1. Below €10,000 the cash capital is paid in full and the special reserve applies; at €10,000 or more, generally at least 25% of cash contributions is paid at incorporation, but a sole shareholder pays in full. Ask the notary to specify fee, taxes, register charges, copies and any extra deed in writing.
Continuing and conditional costs
The Chamber annual duty is due to the competent Chamber for registered businesses; confirm the applicable year, form and local measures rather than copying a generic national amount. Compare the same number of accounting entries, VAT filings, annual returns and ordinary questions when requesting bookkeeping quotes. PEC, digital-signature, invoicing, registered-office and bank-account charges depend on your provider and what is actually required or purchased.
INPS is not a fixed annual fee payable by every director. A director receiving compensation, a working shareholder, an artisan or merchant sole trader and a professional can have different schemes and contribution bases; specify each person's work and remuneration for an individual calculation. Occasional notarial deeds, payroll, cross-border tax advice and sector permits are conditional, not automatic annual charges.
For a non-resident, request separate prices for translations, apostilles/legalisation where needed, a power of attorney, visa help and bank onboarding. A deposit or minimum balance retained in your account is not a consumed setup fee. The bank decides its own KYC requirements; read the bank account preparation guide.
Compare written quotes, not supposed tariffs
For each quote, record: legal form; one-off fee versus annual fee; taxes and disbursements; VAT on fees; capital paid in; number of filings and consultations included; extra work billed separately; and the first renewal date. Art. 9, D.L. 1/2012 abolished professional tariffs: a notary or commercialista quote is not an official fixed price list. Do not infer a fair market range from a fee table without a dated, comparable dataset. The guide to selecting an English-speaking commercialista provides questions to ask about scope and communication.
What the setup-cost planner can and cannot price
The company setup-cost planner organises figures you enter from itemised quotes by legal form and by one-off versus recurring expense; it is not a published fee schedule or a professional quote. Ask the notary, Chamber, accountant and providers for current amounts specific to your activity and location. Do not put a capital contribution or a bank deposit in the consumed-fee column, and do not assume a conditional line applies to every founder.
Use the planner for consumed one-off and recurring amounts. Outside the planner, make a separate cash-needed total including capital, deposits and working capital. Model VAT, income tax, contributions, payroll and visas separately rather than hiding them in an incorporation total. The company-formation overview and step-by-step procedure answer the structure and filing questions respectively.
If you want the corporate file — deed, tax code, VAT position and registrations — handled together, the studio's company formation service sets out the scope before work starts; the guide to opening a company for foreigners is the wider roadmap.
Where taxes belong in your budget
Tax on profits, VAT and social contributions are not incorporation fees. An SRL/SRLS and a sole trader use different tax bases; the amount of profit withdrawn versus retained and the founder's work determine further liabilities. For the tax and contribution decision, read the legal-form comparison and try its scenario calculator, checking the model's assumptions before using any result in a real budget. For transaction-specific VAT, see the VAT guide.
Worked budget template, not a price estimate: enter your own amounts for the notarial quote, Chamber filing, optional setup advice and digital services in the one-off column; enter annual Chamber duty, accounting, PEC, software and any payroll in the recurring column. Keep share capital, deposits and working capital in a separate cash-needed column. Ask a professional to model taxes, INPS roles and contributions separately. If a line does not apply to your activity, mark it “not applicable” rather than assigning it a universal price of zero.
Ways to Reduce Costs
Use Online Registration
An SRL can be incorporated with a deed signed digitally through the notary's platform. That changes the logistics — fewer physical visits, documents exchanged electronically — not the notary's role or the need for a complete file. Ask for an itemised quote and compare the same lines across notaries instead of assuming a standard discount.
Choose the Right Region
IRAP rates differ by region, and professional fees differ by firm, complexity and the state of your file. There is no published regional price list for notarial or accounting work, so choosing a city for its fees is not a reliable saving on its own; weigh the business ecosystem, your clients and the quality of life you need instead.
Use Standard Templates
For an SRLS the deed must use the standard ministerial model, and some notaries offer standard bylaws for simple SRLs. That reduces drafting work rather than the notarial act itself: ask what the quoted package includes — deed, registration, copies, VAT — before comparing it with a bespoke quote.
Handle Some Tasks Yourself
Bookkeeping, invoicing and some filings can be managed in-house. A VAT taxpayer can transmit electronic invoices directly through the Revenue Agency's tools, PEC or an accredited channel; using an intermediary is not generally compulsory for e-invoicing. Agree who prepares, signs and transmits each return or filing, and obtain professional assistance where the specific task or your circumstances require it.
Bundle Services
Ask for one annual fee covering accounts, returns, payroll and ordinary questions, and compare the scope line by line. A reduction means little if a filing or a payroll run is excluded, and published discount percentages are not a benchmark for your own file.
Timeline and Cash Flow Considerations
Plan by dependency, not by a promised date
There is no statutory end-to-end formation time. The notarial deed can be scheduled quickly once the notary has a complete file; what usually sets the real launch date is the slower work around it — the tax code and any power of attorney, the foreign-document formalities the notary asks for, sector authorisations, activation of the VAT position and bank onboarding. Give each dependency an owner and a next action, keep a live list of what the notary still needs, and avoid committing to a launch date that assumes they all finish in parallel.
Cash Flow Planning
Before incorporating, separate capital from expenses. Share capital is not consumed: an SRL can be incorporated from €1, and below €10,000 the capital must be paid in full, with part of annual net profit allocated to a special reserve until capital plus reserve reaches €10,000 (art. 2463, Italian Civil Code). What you actually spend is professional fees, public charges and the cost of running the company before revenue arrives. Set working capital for the months you expect to operate at a loss, keep a reserve for professional fees, and add personal living costs if you are relocating. A single "minimum capital" figure is not a budget.
Foreign-Specific Considerations
Non-resident directors and shareholders
A non-resident director or shareholder does not automatically need an Italian fiscal representative. Whether the company needs a representative, direct identification or a different VAT arrangement depends on the activity and on the rules for non-resident VAT taxpayers (art. 17, D.P.R. 633/1972), and it must be checked for the specific case rather than budgeted as a fixed annual cost. The other practical constraint is bank onboarding: prepare the ownership chart, source-of-funds evidence, corporate documents and business plan, and expect the bank — not the adviser — to decide. If you plan to live in Italy, keep visa and relocation costs in a separate line of the budget.
EU Citizens
EU citizens have easier access but should still budget for moving and housing setup, Italian language services initially, and integration into local business networks.
Frequently Asked Questions
How much does it cost to open an SRL in Italy?
The illustrative table above gives a subtotal of €855.87 to €875.87 for an ordinary SRL, or €609.87 to €629.87 for an SRLS using the standard deed in person, under the stated assumptions. This is not a complete first-year quote: add any additional filings, book stamping, local charges, professional fees and operating costs that apply. The notary quotes the ordinary SRL deed, and the accountant quotes setup and annual work. Share capital is paid into the company, not consumed as a fee.
Can I open a company in Italy without living there?
Yes, you can incorporate and own an Italian company without being an Italian resident, using a power of attorney where the notary accepts one. Residency is a separate question from ownership: a non-resident director does not automatically need a fiscal representative, but the company's VAT position and the bank's KYC requirements must be assessed for the case. Bank onboarding can often start remotely; whether an in-person step is required is the provider's decision, not a rule you can plan around.
What is the cheapest way to start a business in Italy?
The least expensive formation fee alone does not establish the cheapest business structure. A sole proprietorship requires no corporate deed, but has personal liability and its own tax and contribution rules; an SRLS can use the standard notarial deed with specified statutory exemptions, but retains company accounting duties. Ask for matching first-year quotes and assess the applicable tax regime rather than assuming forfettario eligibility. See the structure comparison.
How are Italian companies taxed?
Companies pay IRES at 24% on taxable profit and IRAP at the regional rate, which starts from a 3.9% standard rate and is adjusted by regions. VAT at 22% applies to taxable supplies under the rules and exemptions of the VAT code. Dividends paid to individual shareholders are generally subject to a 26% domestic withholding, reduced by an applicable treaty. The forfettario regime is not available to companies: it is an individual regime, and its 5% rate applies only in the first five periods and only when the startup conditions are met.
A practical cost-check before you incorporate
List the founder's activity and roles, request matching notarial and accounting scopes, ask the competent Chamber about public charges, and compare recurring costs alongside formation costs. Enter these figures in the setup-cost planner to organise your quotes. Then use the SRL versus sole-trader guide and comparison calculator to examine the legal-form decision, including contributions the cost planner cannot resolve.
Sources
- Italian Civil Code, arts. 2463, 2463-bis and 2464 — consolidated text (Normattiva) — minimum capital, payment and reserve rules, and the public deed required for an SRLS.
- D.L. 1/2012, art. 3(3) — standard SRLS incorporation exemptions (Normattiva) — exemption from stamp duty, registry secretarial charges and notarial honoraria; it does not remove the public-deed requirement.
- D.L. 1/2012, art. 9 — abolition of regulated professional tariffs (Normattiva) — quoted professional work has no compulsory universal fee table.
- Unioncamere — annual Chamber duty — check the applicable year and Chamber rather than using an undated flat estimate.
- Law 190/2014, art. 1 — forfettario regime (Normattiva) — the €85,000 ceiling, the exclusions and the 5% startup conditions.
- D.P.R. 633/1972, art. 17 — non-resident VAT taxpayers and the fiscal representative (Normattiva) — the rules that govern whether a representative is needed, instead of an automatic requirement for every non-resident director.
- Revenue Agency — sending electronic invoices — direct transmission options as well as use of an intermediary.
- D.P.R. 131/1986, Tariff, Part I, art. 4 — registration tax on company deeds (Normattiva) — fixed €200 tax on a deed of incorporation with cash contributions.
- D.P.R. 642/1972, Tariff, art. 1, para. 1-bis.1 — stamp duty on company deeds (Normattiva) — flat €156 for the deed, its copy and the Business Register application.
- D.P.R. 641/1972, Tariff, art. 23 — tax on company books (Normattiva) — €309.87 a year, €516.46 above €516,456.90 of share capital.
- Chamber of Commerce of Bergamo — annual fee for 2026 — amounts for new registrations under MIMIT note no. 9347 of 16 January 2026 and the 20% increase authorised by the Ministerial Decree of 17 March 2026.
Public charges checked on 17 November 2026 against the sources above. Professional and notarial fees have no statutory price list: obtain itemised quotes before committing.
 Giovanni EmmiPublished: Updated: